
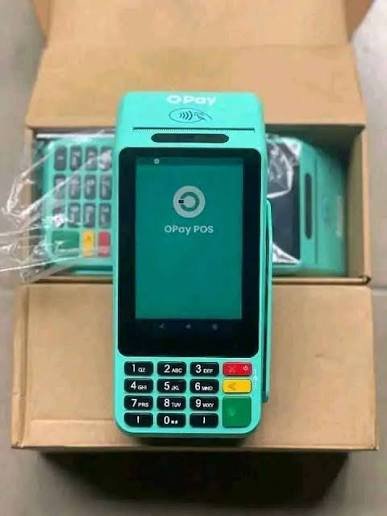
Nigerian merchants and small business owners are being warned about fake OPay applications allegedly being used by fraudsters to generate convincing transfer alerts, screenshots and receipts without any money actually entering the victim’s account.
The fraudulent applications, reportedly distributed outside official app stores, can imitate aspects of the OPay interface and create the appearance of successful payments. Merchants who rely on SMS alerts, screenshots or notification sounds instead of checking their own account balance and transaction history risk releasing goods or services before confirming payment.
Key Highlights
- Fraudsters are reportedly using fake OPay applications to simulate successful transfers.
- Clone applications can generate fake balances, transfer confirmations, screenshots and receipts.
- Some fraudulent tools are distributed as APK files through unofficial websites, social media and messaging platforms.
- Merchants are advised to verify every payment directly in their official OPay account before releasing goods.
- An SMS, email notification, screenshot or transfer receipt should not be treated as proof that funds have entered an account.
- OPay warns users to be cautious of copycat applications and to access its services through the official OPay mobile app.
- OPay Digital Services Limited is listed by the Central Bank of Nigeria as a licensed mobile money operator.
How Fake OPay Apps Work
The scam involves applications designed to imitate legitimate financial platforms and create the appearance of successful transactions.
Some of the applications circulating online have reportedly used names such as OPay Pro, OPay Beta, OPay Max and OPay Adder. They are generally distributed as APK files through unofficial websites, Telegram channels and social media platforms rather than through legitimate app stores.
According to reports and demonstrations shared online, some of these applications can display a selected account balance, generate simulated incoming transfers and produce screens or receipts designed to resemble genuine transaction confirmations.
Other tools reportedly allow users to create fake SMS or email notifications that appear to confirm a payment.
The existence of such tools means that a notification appearing on a merchant’s phone does not by itself establish that a transaction has been completed.
Read also:
- Nigerians Demand Tough Punishment As Police Arrest 27-Year-Old Woman Over Fake OPAY Shutdown Notice
- Fake Christmas Alert: Opay slams viral ₦5,000 giveaway claim, warns Nigerians of festive scammers
Why Merchants Are Vulnerable
The scam exploits the speed at which many small businesses operate.
In busy markets, restaurants, fashion businesses, online shops and POS outlets, merchants may rely on the sound of a payment alert or a customer’s screenshot rather than opening their own financial application to confirm the transaction.
Fraudsters can exploit this practice by presenting a convincing screenshot or generating a notification that appears to show a successful transfer.
The safest verification method is to check the merchant’s own OPay account for the transaction and confirm that the balance has actually increased.
A transaction that does not appear in the recipient’s account should be treated as unpaid, regardless of what the sender’s phone displays.
Fake Receipts And Transfer Screenshots
The problem extends beyond OPay.
Fraudsters can use digital tools to create fraudulent payment receipts and screenshots involving several financial platforms. Reports have also identified tools capable of generating fake receipts associated with services including PalmPay and Kuda.
This makes the issue broader than any single fintech platform.
The common feature is the attempt to create false evidence of payment and persuade the recipient to release goods, cash or services before the transaction has been independently verified.
OPay Warns Against Copycat Applications
OPay has warned customers about fraudulent websites and applications designed to imitate its platform.
The company’s security guidance advises users to access its services exclusively through the official OPay mobile application and to be cautious of copycat applications that resemble the company’s platform. It also recommends reviewing transaction history regularly and reporting unexplained transactions.
OPay remains a legitimate financial technology company operating in Nigeria. The Central Bank of Nigeria lists OPay Digital Services Limited among licensed mobile money operators.
The company has also recently dealt with other forms of online impersonation. In September 2026, OPay denied a false social media claim that it would shut down its Nigerian operations, while the Nigeria Police Force National Cybercrime Centre later announced an arrest in connection with the circulation of the forged notice.
What Merchants Should Do
Merchants can reduce their exposure to fake transfer scams by adopting a simple payment verification procedure.
First, check your own account. Open the official OPay application and confirm that the payment appears in both the account balance and transaction history.
Second, do not rely on screenshots. A screenshot can be edited or generated by a fraudulent application and should not replace independent verification.
Third, ignore notification sounds as proof of payment. An alert sound or SMS is not sufficient evidence that funds have been credited.
Fourth, avoid unofficial applications. Do not install APK files or applications claiming to be modified versions of OPay or other financial platforms.
Fifth, verify high-value transactions before releasing goods. Where the payment is substantial, merchants should take additional time to confirm the transaction rather than allowing pressure from a customer to determine the process.
Sixth, educate employees. Businesses with multiple staff members should ensure that everyone handling payments understands the risks associated with fake alerts and cloned applications.
Fake Alert Scams Require Greater Vigilance
Fake transfer scams are not new in Nigeria, but the increasing sophistication of digital tools makes it more difficult to distinguish fraudulent payment evidence from genuine transaction confirmations.
The most important safeguard for merchants is therefore independent verification.
A customer can show a screenshot, SMS, email or receipt claiming that a transfer has been completed, but the decisive evidence is whether the money has actually entered the merchant’s account.
Merchants should download financial applications only from official app stores, avoid copycat applications and verify every credit through their own account before releasing goods or services.
For more updates on this and other trending stories, follow us on X.